What Are Sinking Funds? How They Work, With Examples
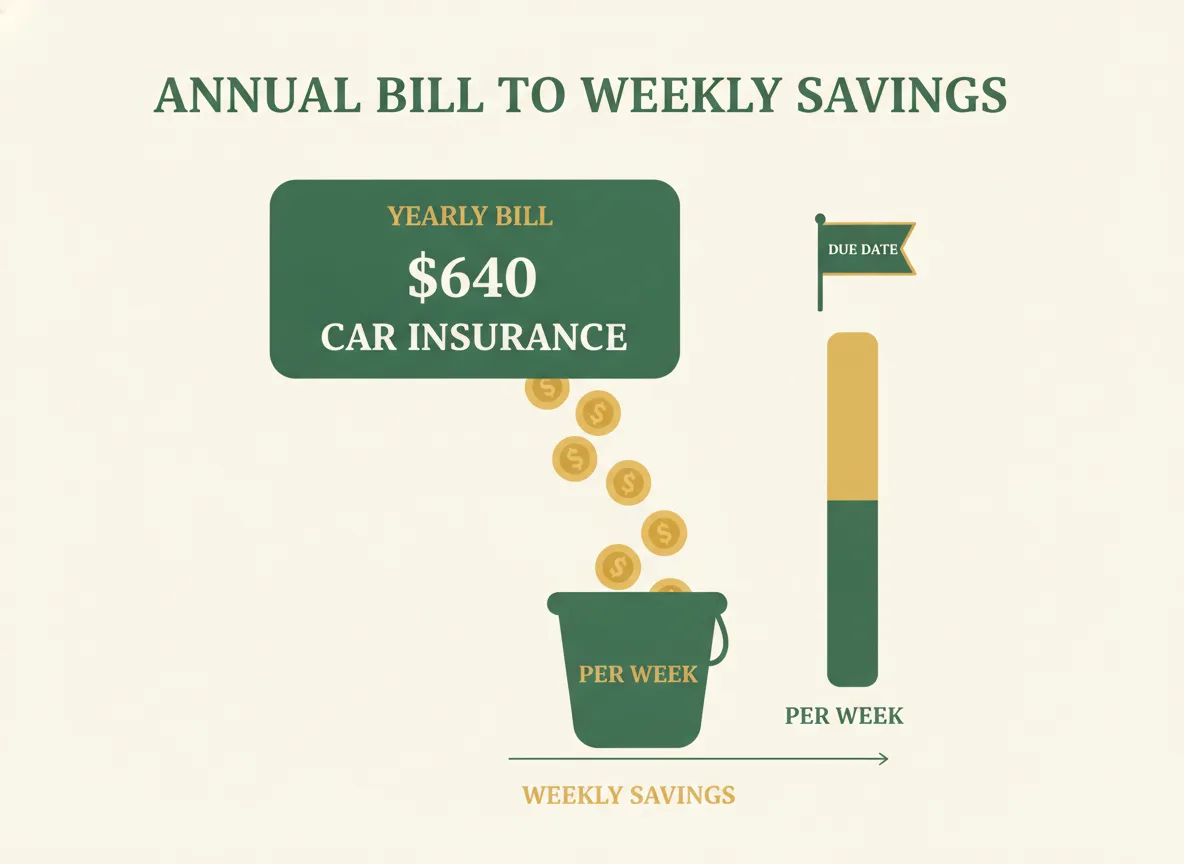
A sinking fund is money you set aside in small, regular amounts for an expense you already know is coming. Instead of facing a large bill all at once, you save a little from each paycheck so the full amount is waiting on the due date. Car registration, an annual insurance premium, holiday gifts and a vet visit can all be sinking funds.
(The same phrase is used in corporate finance for money set aside to repay bonds. This page is about the personal-budget meaning.)
How a sinking fund works
The idea is simple: a big, infrequent cost becomes a small, frequent one.
- Pick an expense with a known or estimated cost and a due date.
- Count how many paychecks or weeks you have until then.
- Divide the cost by that number.
- Set that amount aside every payday, in its own labeled bucket.
- When the bill arrives, pay it from the bucket.
For example, say your car insurance is billed once a year at 1,200. Spread across 52 weeks that is about 23.08 per week. If you are paid every two weeks (26 paychecks), it is about 46.15 per paycheck. If you are paid monthly, it is 100 per month. The bill has not changed. You have only chosen when to feel it.
Sinking funds vs emergency funds vs regular savings
These three are often mixed up, and mixing them causes trouble.
| Sinking fund | Emergency fund | General savings | |
|---|---|---|---|
| Purpose | A known future expense | An unpredictable setback | Open-ended goals |
| Amount | Calculated from the bill | A cushion you choose | Whatever you decide |
| Due date | Yes | No | Often no |
| Spent when | The bill arrives | Something unexpected happens | You reach the goal |
| Example | Annual insurance premium | Sudden loss of income | A future down payment |
The key difference is predictability. If you can write the date on a calendar, it belongs in a sinking fund. If you cannot, it belongs in an emergency cushion. Keeping them separate also keeps you honest: spending the car-registration money on something else does not make the registration go away.
What to put in a sinking fund
A good test: has this expense ever caught you off guard even though it happens every year? Common candidates:
- Annual and semi-annual bills: insurance premiums, vehicle registration, memberships, domain or software renewals.
- Seasonal costs: holiday gifts and meals, back-to-school supplies, summer camp deposits, heating or snow removal.
- Irregular but expected costs: car maintenance and tires, dental work, pet vet visits, home repairs.
- Planned purchases: a new phone, a trip, a piece of furniture.
For a longer list with ideas for each, see sinking funds categories and examples.
How to size each fund
Use this formula:
(Total cost − amount already saved) ÷ number of paychecks until the due date = amount per paycheck
Some practical notes:
- Use a realistic cost. If a bill changes every year, use last year's amount plus a cushion for price increases.
- Use paychecks, not months, when you are paid biweekly. A year has 26 biweekly paychecks, not 24, so dividing by 12 and then by two gives you a slightly wrong answer.
- Start from the nearest due date. If a bill is due in two months, the fund will be large per paycheck. That is normal. Fund the nearest ones first, then add the rest as your budget allows.
- Round up. A slightly high number gives you a margin.
Where to keep the money
There are two common approaches, and either works:
- Separate accounts. Some banks let you create labeled savings sub-accounts or "pockets". The money is physically separate, which makes it harder to spend by accident.
- One account, tracked in a sheet. You keep the money in a single savings account and track each fund's balance in a spreadsheet. This is simpler to open but depends on you keeping the sheet current.
Either way, the tracking matters as much as the saving. Each fund needs a name, a target, a due date and a running balance.
A worked example: five funds on a biweekly paycheck
| Fund | Yearly cost | Per week | Per biweekly paycheck |
|---|---|---|---|
| Car insurance | 1,200 | 23.08 | 46.15 |
| Vehicle registration | 150 | 2.88 | 5.77 |
| Holiday gifts | 600 | 11.54 | 23.08 |
| Vet checkups | 300 | 5.77 | 11.54 |
| Annual software renewals | 120 | 2.31 | 4.62 |
| Total | 2,370 | 45.58 | 91.16 |
The numbers are illustrative. What matters is the pattern: five lumpy yearly costs become one steady line in the budget.
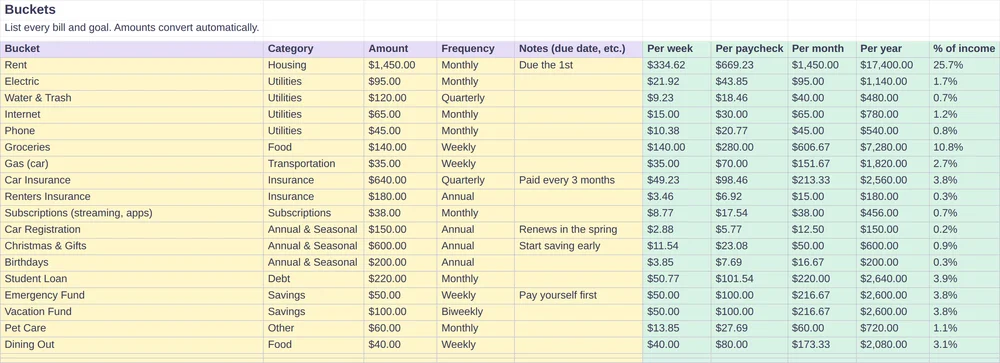
How Bucket Budget Planner handles this
In Bucket Budget Planner, each bill goes in as a bucket with an amount and how often it is due: weekly, biweekly, semi-monthly, monthly, quarterly or annual. The Buckets tab converts every bucket to a per-week, per-paycheck, per-month and per-year amount. That is the same math as above, done for you. The Dashboard then adds everything up so you can see whether your income covers all your buckets and how much is left to spend.
The included web app has a Sinking Funds Calculator where you enter a goal, how much you have already saved and a target date to see what to set aside each week or paycheck, and an Annual Bills Calendar that places yearly and quarterly bills by month. A library of 154 ready-made buckets includes many annual and seasonal costs, and the 2027 Bill Calendar is a printable PDF with twelve months.
Common mistakes
- Forgetting the small ones. One forgotten yearly 60 charge is not a disaster, but five of them in the same month can be.
- Raiding the fund for something else and never paying it back. If you must borrow, write it down and set a repayment date.
- Treating the fund as a target to hit once. When the bill is paid, the fund starts again for next year.
- Starting too big. Begin with the two or three expenses that have hurt most, and add more over time.
Next steps
- Write down every bill that happens less often than monthly.
- Find the amount and due date for each.
- Use the formula above to get a per-paycheck number.
- Put those numbers in one place and watch the balance grow.
For tracking, see how to track sinking funds, and to put due dates on paper, see the 2027 bill calendar. If you want to see how this fits into a whole budget, read about bucket budgeting.
This guide is general information, not financial advice. Your situation may differ.